A simple way to think about it
Equipment financing is a loan or lease used for one clear purpose: buying equipment for your business. Instead of paying the full price up front, you pay over time in regular payments.
In many cases, the equipment itself helps secure the financing. That simply means the lender can look at the value of the equipment, not only at your bank account, when reviewing your request.
Business owners use equipment financing for things like work vehicles, kitchen equipment, medical and dental tools, construction machines, salon equipment, computers, and machines used in a shop or warehouse.
How equipment financing works
The process is usually simple:
- Pick the equipment. Start with a price quote from the seller, so you know the exact amount you need.
- Apply. The lender reviews your business, your income, and your credit history.
- Get a decision and terms. If you are approved, you will see the payment amount, how long the payments last, and the total cost. Read this part carefully before you sign.
- Get your equipment and start paying. You use the equipment in your business while you make your regular payments.
Every lender and program is a little different, so the steps and the paperwork can change. The basic idea stays the same: spread a big purchase into smaller payments you can plan for.
Loan or lease: what is the difference?
These two words come up a lot, and they are not the same.
With an equipment loan, you are buying the equipment. You own it, and when the loan is paid off, it is fully yours.
With an equipment lease, you are paying to use the equipment for a set time. At the end, you may return it, buy it, or trade up to a newer model, depending on the agreement.
Neither one is always better. A loan can make more sense for equipment you plan to keep for many years. A lease can make sense for equipment that changes fast, like some technology. The right choice depends on the equipment, your budget, and how long you plan to use it.
What lenders usually look at
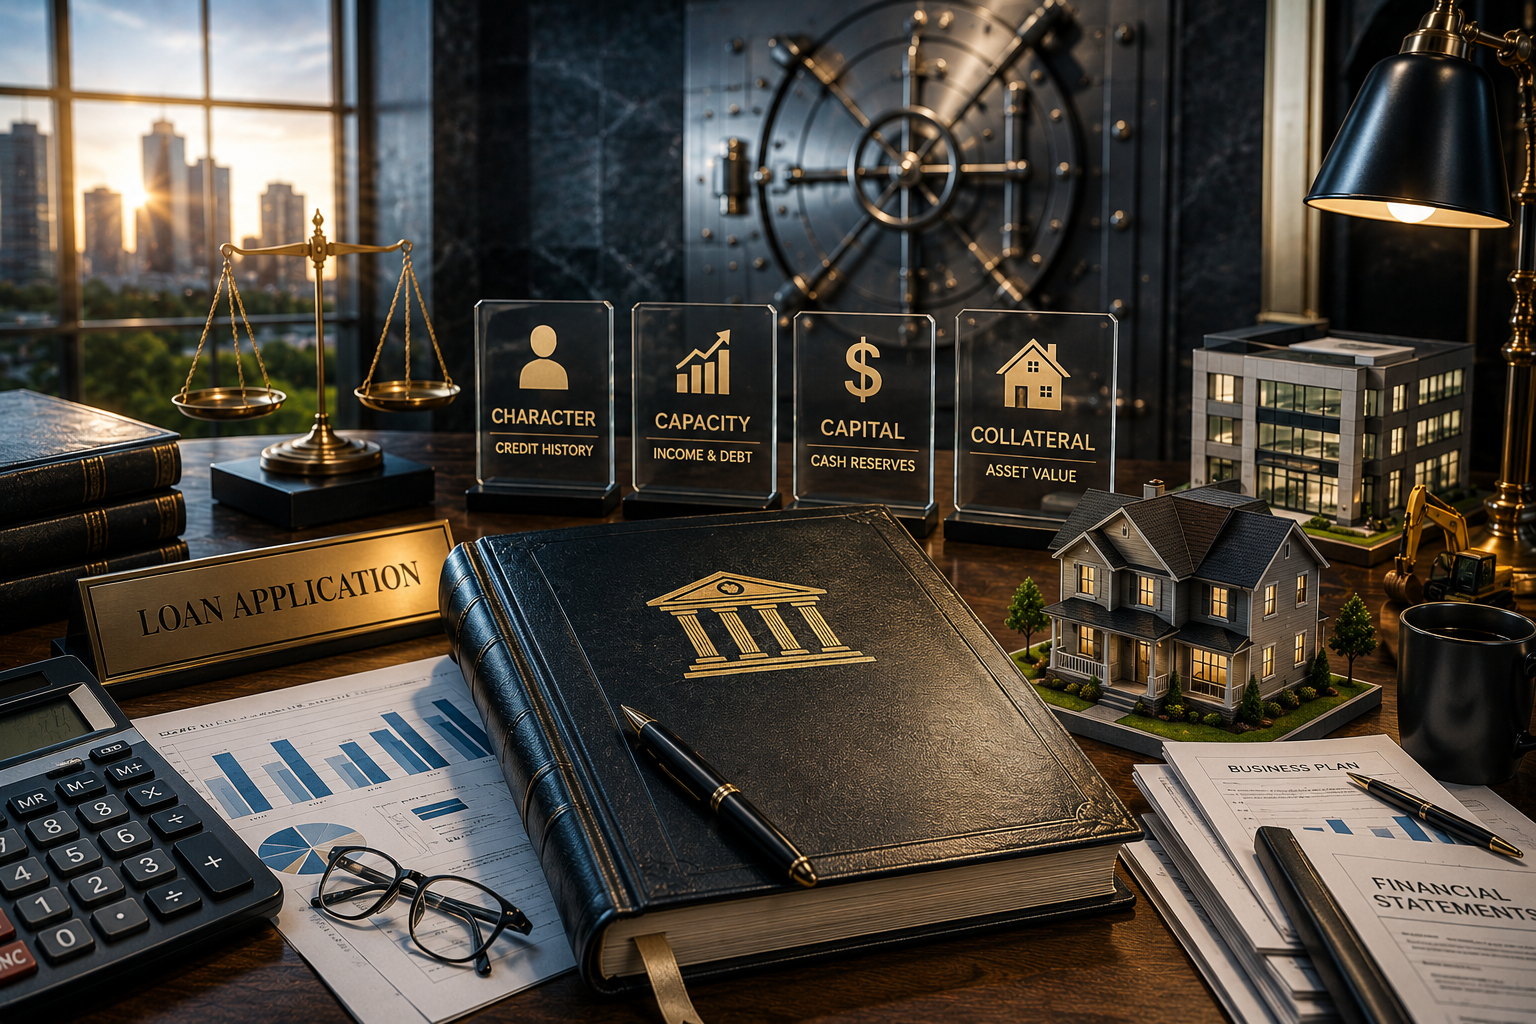
Lenders want to answer one basic question: can this business handle the payment, month after month? To answer it, they often look at:
- Your business and personal credit history
- How long you have been in business
- Your business income and bank statements
- The type of equipment and how long it is expected to last
- How much cash your business keeps on hand
You do not need a perfect record to ask questions or to apply. Many business owners are surprised to learn there may be more than one path. Still, no one can promise an approval, a rate, or exact terms before a real review. Be careful with anyone who does.
The real cost is more than the monthly payment.
A low monthly payment can look great and still be the wrong deal. Before you sign, add up the full picture:
- The total amount you will pay over the full term
- Any down payment and fees at the start
- Insurance and upkeep for the equipment
- What happens if you want to pay it off early
Also think about your slow months. A payment that feels easy in your best month should still fit in a normal month.
Here is a simple, made-up example. Imagine a bakery that needs a new oven. Paying in cash might empty the savings the bakery keeps for slow weeks. Financing the oven spreads the cost out, so the bakery keeps some cash for payroll and supplies while the oven starts earning money right away. The numbers are different for every business, but the idea is the same: protect your cash while you grow.
Get your paperwork ready.
Having your papers in order makes the process smoother. Lenders often ask for:
- A price quote for the equipment
- Recent business bank statements
- Business tax returns
- A photo ID and basic business papers, such as your business license or formation papers
Your list may be shorter or longer. Ask for the full list up front so there are no surprises.
A simple way to decide
Ask yourself four questions:
- Will this equipment help my business earn more, save time, or serve more customers?
- Can my business handle the payment in a normal month, not just a great month?
- How long will this equipment last, and will I still be paying for it after it wears out?
- Have I compared the total cost, not just the monthly payment?
If you can answer those four questions with confidence, you are in a good place to move forward.
Questions about equipment financing?
Every business is different, and a short conversation can save you a long search. If you are thinking about new equipment and want to talk through your options, reach out to JD Agban Group for a
free 30-minute consultation. Send an email to
george.agban@jdagban.com or visit
www.jdagban.com
We will explain your options in plain words, with no pressure.
This article is for education only and is not financial or legal advice. Loan programs, rates, and terms change and depend on each borrower's full review.