Here is what every investor and business owner needs to know about commercial real estate financing options, key approval metrics, and regulatory requirements.
Key Types of Commercial Real Estate Loans
Depending on whether you intend to occupy the space or lease it out for rental income, several loan structures are available:
SBA 504 Loans: Ideal for owner-occupied small businesses (where your business occupies at least 51% of an existing building or 60% of new construction). These government-backed loans offer long-term, fixed-rate financing with low down payments (typically 10%).
Conventional Commercial Mortgages: Issued by commercial banks and credit unions for office buildings, retail centers, industrial warehouses, and multi-family units. They generally require 20% to 30% down and offer 5- to 25-year terms.
Bridge & Short-Term Financing: Used for property acquisitions, quick turnarounds, or repositioning assets before securing long-term debt.
Commercial Construction Loans: Specialized financing used to cover land acquisition and building costs, which transition into permanent loans upon completion.
What Lenders Look For: The 4 Core Metrics
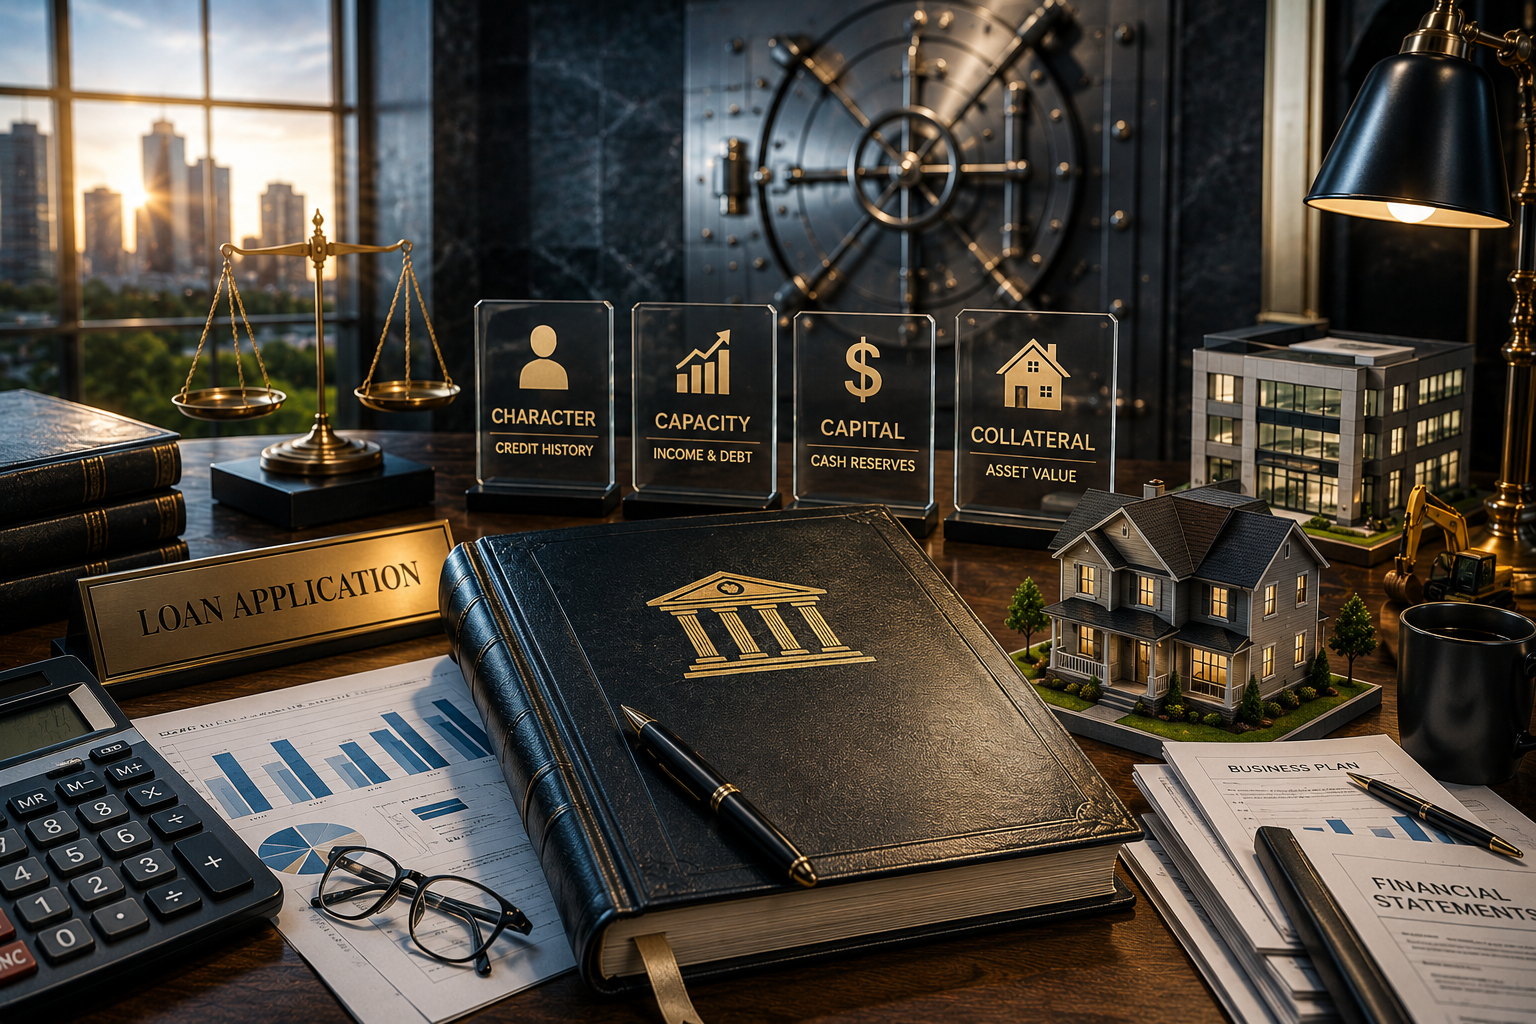
When underwriting a commercial real estate transaction, lenders evaluate four key financial metrics:
- Debt Service Coverage Ratio (DSCR):
Lenders evaluate the property's Net Operating Income (NOI) against its annual debt obligations. Most lenders look for a DSCR of
1.25x or higher, meaning the property generates 25% more income than required to pay its loan payments.
- Loan-to-Value (LTV) Ratio: Commercial loans typically cap LTV between
65% and 80%, requiring borrowers to bring 20% to 35% equity to the closing table.
- Borrower Liquidity & Reserves: Lenders expect borrowers to maintain post-closing liquidity (cash or liquid assets) equal to 6 to 12 months of mortgage payments.
- Creditworthiness & Character: For owner-occupied properties, lenders examine business tax returns, profit and loss statements, and personal credit histories.
Regulatory Compliance & Disclosure Requirements
Navigating commercial real estate loans requires strict adherence to lending regulations and federal guidelines:
- Equal Credit Opportunity Act (ECOA): Ensures fair lending practices without discrimination based on race, color, religion, national origin, sex, marital status, or age.
- Know Your Customer (KYC) & Anti-Money Laundering (AML): Under the USA PATRIOT Act, lenders must verify the identity of ultimate beneficial owners (UBOs) holding 25% or more equity in the borrowing entity (LLC, Corporation, etc.).
- Environmental Due Diligence: Lenders usually require a
Phase I Environmental Site Assessment (ESA) to identify any potential environmental contamination or liabilities on the commercial property prior to funding.
- Commercial Appraisal Compliance: Lenders must engage independent, state-certified commercial appraisers compliant with the Uniform Standards of Professional Appraisal Practice (USPAP).
Next Steps for Borrowers
Before applying for commercial real estate financing:
- Structure your purchasing entity (e.g., an LLC or LP).
- Gather 3 years of business and personal tax returns, financial statements, and rent rolls (if applicable).
- Prepare a clear summary of your project or business operations.
Disclaimer: This article is for informational and educational purposes only and does not constitute financial, legal, or investment advice. Loan terms, interest rates, and approval criteria vary based on property type, lender criteria, and borrower qualifications.